
Waterfront homes can have insurance exposures that differ significantly from properties located farther inland. Proximity to lakes, rivers, bays, or the ocean can increase concerns involving flooding, erosion, wind, docks, seawalls, watercraft, access, and the cost of rebuilding in a specialized location.
Insurance options can vary considerably between companies. Peninsula Insurance Servicescan help clients in Michigan compare available policies and review important differences in coverage, limits, deductibles, eligibility, and exclusions.
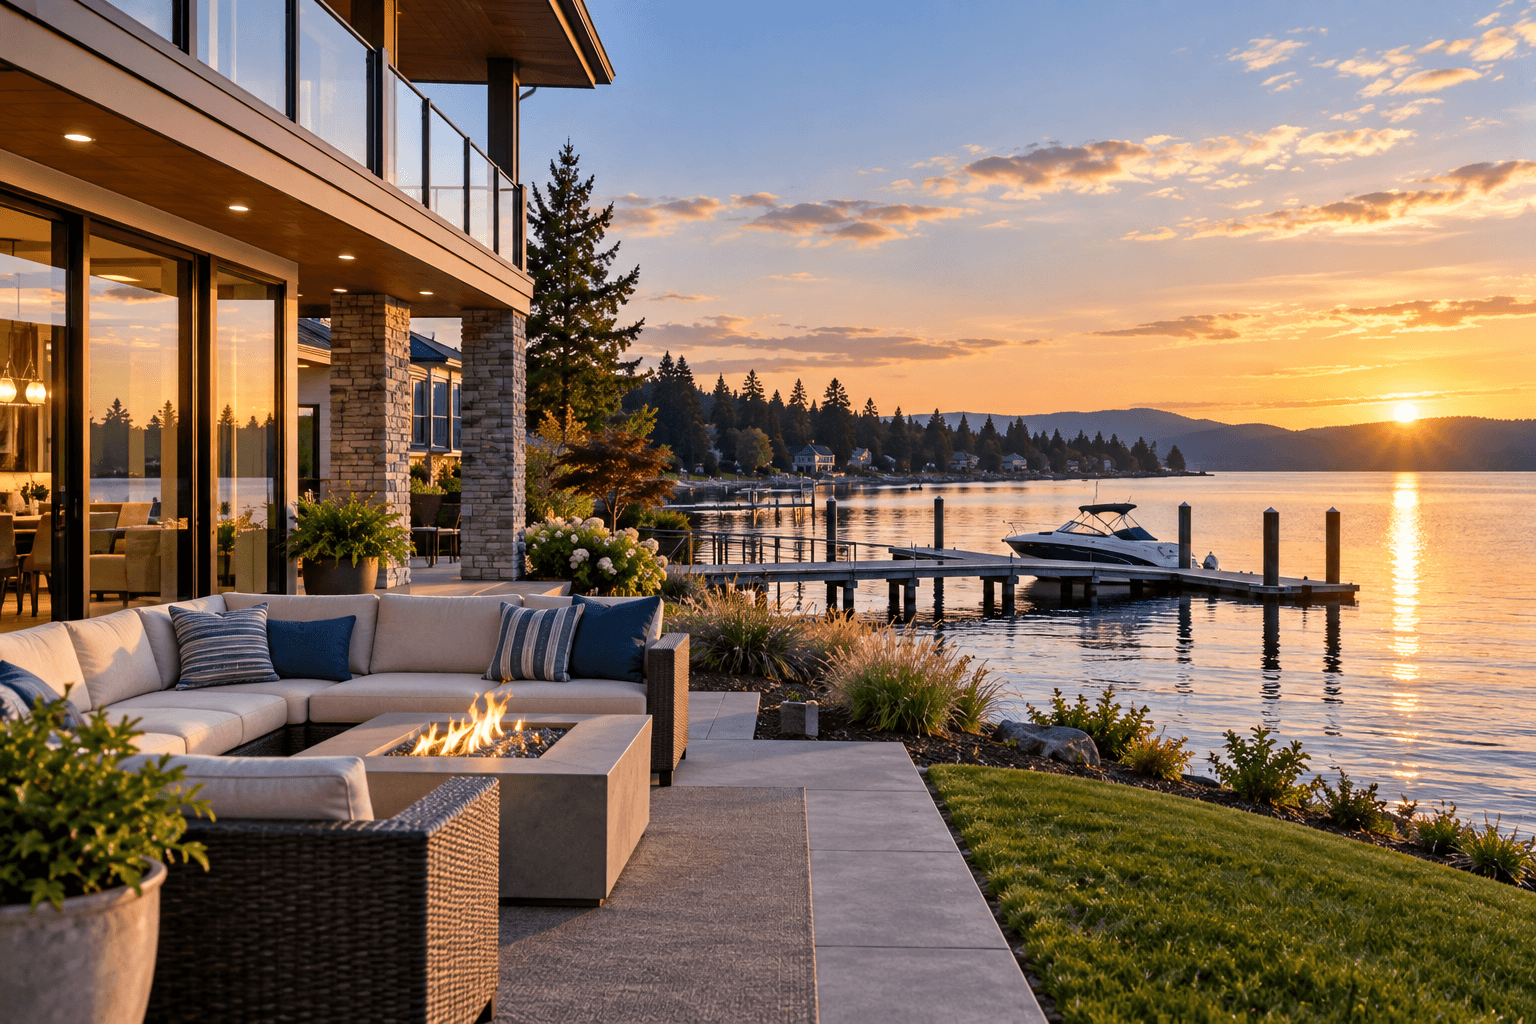
Why Is Waterfront Home Insurance Important?
A standard homeowners policy may address many ordinary property and liability risks, but it generally should not be assumed to cover flood, shoreline movement, or every waterfront structure. The home’s location, elevation, construction, distance from water, protective features, and local catastrophe exposure can all affect available coverage.
The goal is not simply to purchase a policy, but to build coverage around the actual exposures. Services offered, property values, employees, locations, contracts, prior losses, and other details can all affect the insurance companies and options available.
Insurance Coverage to Consider
The right insurance program depends on the individual risk. Depending on the business or property, several types of coverage may work together rather than relying on a single policy.
Dwelling and Other Structures Coverage
Homeowners insurance may protect the dwelling and eligible detached structures against covered causes of loss, subject to limits, deductibles, and exclusions.
Flood Insurance
Standard homeowners insurance generally excludes flooding. Separate flood insurance may be important for waterfront properties even when a lender does not require it.
Windstorm Coverage
Coastal or wind-exposed properties may have separate wind deductibles, exclusions, or stand-alone windstorm policies depending on location and insurer.
Dock and Waterfront Structure Coverage
Docks, piers, boathouses, lifts, seawalls, and similar structures may have special limits or exclusions and should be specifically reviewed with the insurer.
Personal Liability Coverage
Liability protection may help with certain covered injuries occurring on the property, but swimming areas, docks, watercraft, rentals, and other exposures should be disclosed.
Additional Living Expense Coverage
If a covered loss makes the home uninhabitable, additional living expense coverage may help with certain temporary housing and increased living costs.
Choosing Waterfront Home Insurance in Michigan
Insurance companies can differ in what they are willing to insure, how they define covered operations or property, the limits and deductibles they offer, and the exclusions or endorsements included with a policy. Those differences can become especially important when a risk has specialized equipment, professional services, unusual property features, higher values, or other exposures that fall outside a standard insurance profile.
An independent insurance agency can compare options from multiple insurance companies and help identify questions that should be addressed before coverage is placed. Peninsula Insurance Servicescan help review the details of the risk, discuss available insurance options, and explain how different policies may respond.
Coverage availability and requirements vary by insurer and by situation. Policies contain conditions, exclusions, limits, and definitions that determine how coverage applies. Review the actual policy and discuss questions with an insurance professional before making coverage decisions.
Waterfront Home Insurance FAQs
Does homeowners insurance cover flooding at a waterfront home?
Generally no. Standard homeowners policies typically exclude flood, so separate flood insurance may be needed for rising water, storm surge, or similar events.
Are docks and boat lifts covered by waterfront home insurance?
They may have limited coverage or require specific endorsements. Docks, piers, lifts, boathouses, and seawalls should be discussed individually with the insurer.
Does waterfront home insurance cover erosion or shoreline movement?
Earth movement, erosion, and gradual shoreline loss are commonly excluded or restricted. Specialized options are limited and policy wording should be reviewed carefully.
Is waterfront home insurance more expensive than standard homeowners insurance?
It can be, depending on flood and wind exposure, rebuilding cost, location, claims history, access, protective features, and the availability of insurers in the area.
Our Recent Blog Posts
 Michigan Auto Insurance Rates: What Impacts Your Premium?August 22, 2026 - 11:16 pm
 Short Term Rental Insurance: A Practical Guide for HostsAugust 19, 2026 - 11:13 pm
 Tire SafetyAugust 10, 2026 - 2:38 pm
 Matching Your Classic Car Insurance to Your Use and NeedsJuly 21, 2026 - 11:35 pm
 Understanding Swimming Pool LiabilityJuly 9, 2026 - 11:25 pm
 Preparing Your Camper Trailer For Summer Adventures: 6 Essential StepsJune 23, 2026 - 7:34 pm
Love Our Service? Leave Us A Review!

