
Owners of medical and professional office buildings need insurance focused on the real estate and lessor exposure rather than the professional services performed by tenants. Buildings may be leased to physicians, dentists, attorneys, accountants, therapists, or other professional occupants, each of which can affect underwriting.
Insurance needs can vary significantly from one risk to another. Peninsula Insurance Services can help clients in Michigan compare available options from insurance companies and review important differences in coverage, limits, deductibles, eligibility, and exclusions.
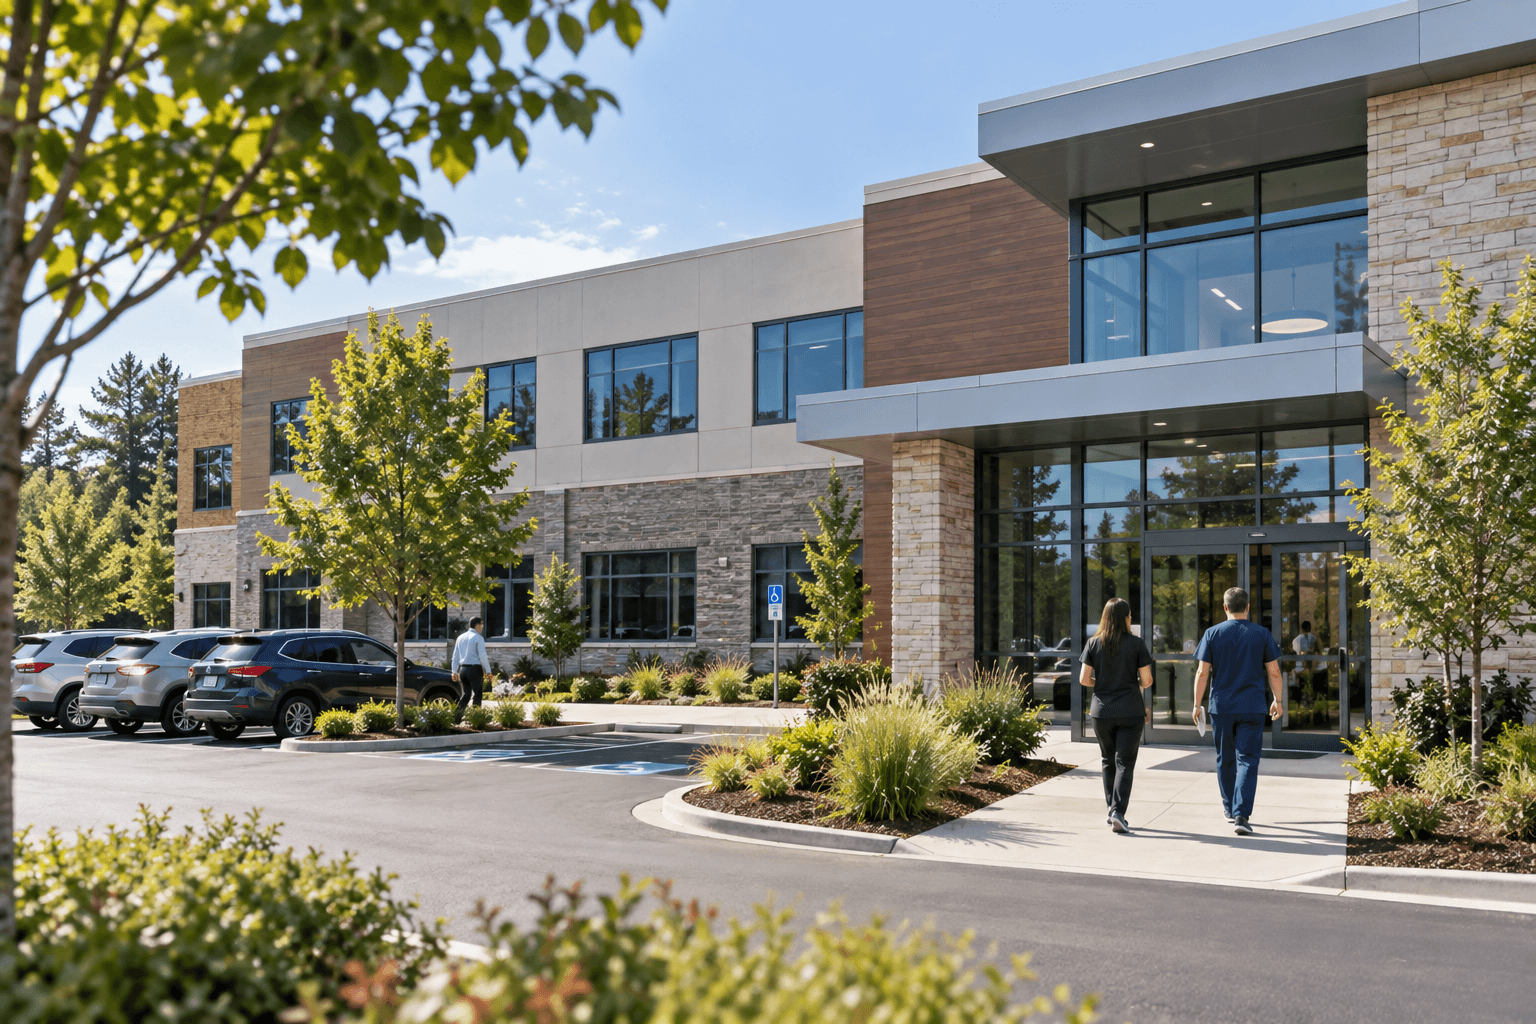
Why Is Medical & Professional Office Building Insurance Important?
A single insurance policy does not necessarily address every exposure. Property values, location, occupancy or use, contracts, equipment, employees, liability exposures, prior losses, and other characteristics can all influence which policies and insurance companies may be appropriate.
Taking time to identify those details before coverage is placed can help reduce gaps and make it easier to compare policies on more than price alone.
Coverage to Consider for Medical & Professional Office Building Insurance
The coverage needed depends on the specific risk. Depending on the property, vehicle, business, or personal assets being insured, several types of coverage may work together.
Commercial Building Coverage
Commercial building coverage may protect the insured structure against covered causes of loss, subject to valuation, deductibles, and policy terms.
Lessor’s Risk General Liability
Lessor’s risk liability may help with certain covered bodily injury or property damage claims arising from ownership and common-area responsibilities.
Rental Value and Business Income
Rental-value coverage may help replace eligible rental income when covered property damage prevents tenants from occupying the building.
Equipment Breakdown Coverage
Equipment breakdown may help with certain sudden mechanical or electrical failures involving covered HVAC, electrical, mechanical, or other building equipment.
Ordinance or Law Coverage
Ordinance or law coverage may help with certain increased costs caused by enforcement of current building codes after a covered loss.
Umbrella or Excess Liability
Umbrella or excess liability may provide additional limits above qualifying underlying liability policies for certain covered claims.
Choosing Medical & Professional Office Building Insurance in Michigan
Insurance companies can differ in the risks they will insure, how property or operations are valued, the limits and deductibles they offer, and the exclusions or endorsements included with a policy. Specialized risks can make those differences especially important.
An independent insurance agency can compare options from multiple insurance companies and help identify questions that should be addressed before coverage is placed. Peninsula Insurance Services can help review the details, discuss available insurance options, and explain how different policies may respond.
Coverage availability and requirements vary by insurer and situation. Policies contain conditions, exclusions, limits, and definitions that determine how coverage applies. Review the actual policy and discuss questions with an insurance professional before making coverage decisions.
Medical & Professional Office Building Insurance FAQs
Does the building owner’s policy cover a medical tenant’s malpractice claims?
Generally no. Professional tenants should maintain their own professional liability and business insurance. The building owner’s policy focuses on ownership and lessor exposures.
Does tenant type matter when insuring an office building?
Yes. Medical, dental, legal, financial, and other professional occupancies can have different property, equipment, visitor, and building-system exposures.
Can the owner insure lost rent after a covered property loss?
Rental-value coverage may help replace eligible rental income when covered damage makes leased space temporarily unusable.
Should tenants name the landlord as an additional insured?
Lease agreements often include insurance and additional-insured requirements. Those provisions should be coordinated with legal counsel and the parties’ insurance policies.
Our Recent Blog Posts
 Michigan Auto Insurance Rates: What Impacts Your Premium?August 22, 2026 - 11:16 pm
 Short Term Rental Insurance: A Practical Guide for HostsAugust 19, 2026 - 11:13 pm
 Tire SafetyAugust 10, 2026 - 2:38 pm
 Matching Your Classic Car Insurance to Your Use and NeedsJuly 21, 2026 - 11:35 pm
 Understanding Swimming Pool LiabilityJuly 9, 2026 - 11:25 pm
 Preparing Your Camper Trailer For Summer Adventures: 6 Essential StepsJune 23, 2026 - 7:34 pm
Love Our Service? Leave Us A Review!

